Introduction
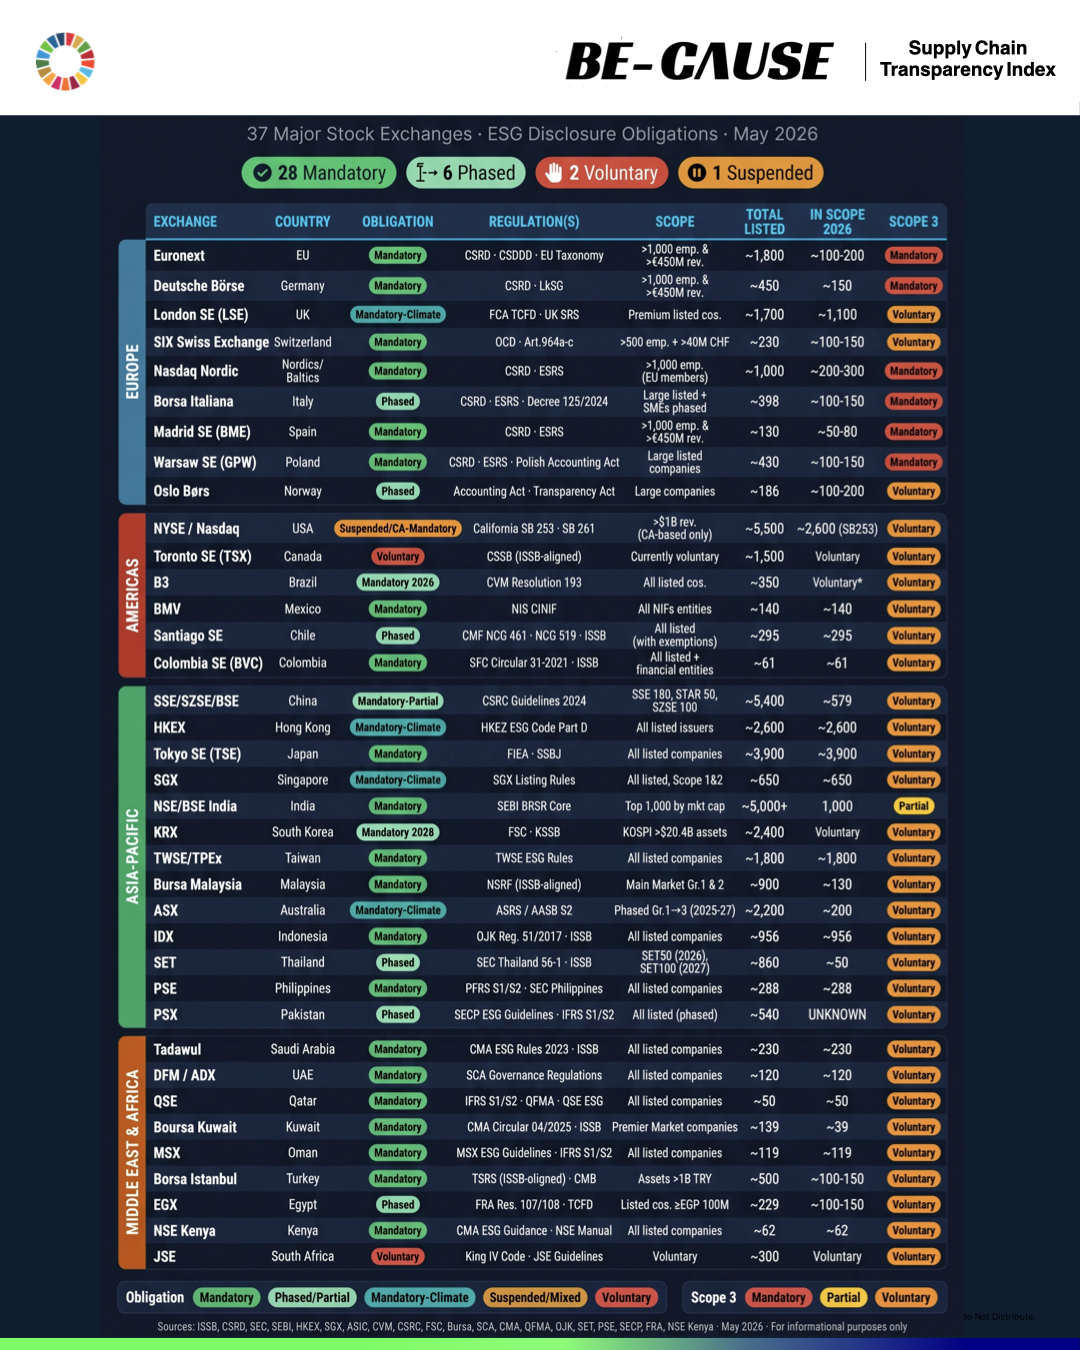
The landscape of ESG (Environmental, Social, and Governance) regulation has experienced unprecedented acceleration, transitioning from voluntary frameworks to strict, standardized reporting obligations. This mapping structures the ESG disclosure requirements of 37 major global stock exchanges, highlighting applicable regulations, scope, obligation levels, the status of Scope 3, and enforcement mechanisms.
As of May 2026, the picture across these 37 venues breaks down as 28 Mandatory regimes, 6 Phased rollouts, 2 Voluntary, and 1 Suspended (the US federal SEC climate rule, with California's SB 253 / SB 261 acting as a de facto mandatory layer for companies operating in the state).
One caveat runs through the whole map. ‘Listed’ usually means listed shares. Companies that only list bonds are often outside these regimes. Section 3.5 explains where.
The year 2026 marks a decisive turning point with the entry into force of numerous regulations aligned with the International Sustainability Standards Board (ISSB) standards and the revision of the Corporate Sustainability Reporting Directive (CSRD) in Europe following the Omnibus package.
1. Regulatory Mapping by Stock Exchange
The table below presents a structured overview of ESG obligations for 37 major global stock exchanges, including the status of Scope 3 disclosure — the single most strategic indicator for buyers managing value-chain risk.
| Exchange | Country / Region | Obligation Level | Applicable Regulation(s) | Scope | Scope 3 Status | In-Scope 2026 |
|---|---|---|---|---|---|---|
| Euronext (Paris, Amsterdam, etc.) | European Union | Mandatory | CSRD · CSDDD · EU Taxonomy | >1,000 emp. & >€450M rev. | Mandatory | ~100–200 |
| Deutsche Börse | Germany | Mandatory | CSRD · LkSG | >1,000 emp. & >€450M rev. | Mandatory | ~150 |
| London Stock Exchange (LSE) | United Kingdom | Mandatory-Climate | FCA TCFD · UK SRS (ISSB-aligned) | Premium listed companies | Voluntary | ~1,100 |
| SIX Swiss Exchange | Switzerland | Mandatory | OCD · Code of Obligations Art. 964a-c | >500 emp. & >40M CHF rev. | Voluntary | ~100–150 |
| Nasdaq Nordic | Nordics / Baltics | Mandatory | CSRD · ESRS | >1,000 emp. (EU members) | Mandatory | ~200–300 |
| Borsa Italiana | Italy | Phased | CSRD · ESRS · Decree 125/2024 | Large listed + SMEs phased | Mandatory | ~100–150 |
| Madrid SE (BME) | Spain | Mandatory | CSRD · ESRS | >1,000 emp. & >€450M rev. | Mandatory | ~50–80 |
| Warsaw SE (GPW) | Poland | Mandatory | CSRD · ESRS · Polish Accounting Act | Large listed companies | Mandatory | ~100–150 |
| Oslo Børs | Norway | Phased | Accounting Act · Transparency Act | Large companies | Voluntary | ~100–200 |
| NYSE / Nasdaq | United States | Suspended (federal) / CA-Mandatory | SEC Climate Rule (suspended) · California SB 253 · SB 261 | >$1B revenue (CA-based only) | Voluntary | ~2,600 (SB 253) |
| Toronto SE (TSX) | Canada | Voluntary | CSSB (ISSB-aligned) | Currently voluntary | Voluntary | Voluntary |
| B3 (Brasil Bolsa Balcão) | Brazil | Mandatory 2026 | CVM Resolution 193 (ISSB-aligned) | All listed companies | Voluntary* | Voluntary |
| Bolsa Mexicana de Valores (BMV) | Mexico | Mandatory | NIS CINIF | All NIFs entities | Voluntary | ~140 |
| Santiago SE | Chile | Phased | CMF NCG 461 · NCG 519 · ISSB | All listed (with exemptions) | Voluntary | ~295 |
| Colombia SE (BVC) | Colombia | Mandatory | SFC Circular 31-2021 · ISSB | All listed & financial entities | Voluntary | ~61 |
| SSE / SZSE / BSE | China | Mandatory-Partial | CSRC Sustainability Reporting Guidelines (2024) | SSE 180, STAR 50, SZSE 100, dual-listed | Voluntary | ~579 |
| Hong Kong Exchange (HKEX) | Hong Kong | Mandatory-Climate | HKEX ESG Code (Part D) | All listed issuers | Voluntary | ~2,600 |
| Tokyo Stock Exchange (TSE) | Japan | Mandatory | FIEA · SSBJ Standards (ISSB-aligned) | All listed companies | Voluntary | ~3,900 |
| Singapore Exchange (SGX) | Singapore | Mandatory-Climate | SGX Listing Rules | All listed (Scope 1 & 2) | Voluntary | ~650 |
| NSE / BSE | India | Mandatory | SEBI BRSR Core | Top 1,000 by market cap | Partial | ~1,000 |
| Korea Exchange (KRX) | South Korea | Mandatory 2028 | FSC Roadmap · KSSB (ISSB-aligned) | KOSPI > $20.4B assets | Voluntary | Voluntary |
| Taiwan Stock Exchange (TWSE / TPEx) | Taiwan | Mandatory | TWSE ESG Rules | All listed companies | Voluntary | ~1,800 |
| Bursa Malaysia | Malaysia | Mandatory | NSRF (ISSB-aligned) | Main Market Group 1 & 2 | Voluntary | ~130 |
| Australian Securities Exchange (ASX) | Australia | Mandatory-Climate | ASRS / AASB S2 | Phased Group 1→3 (2025–27) | Voluntary | ~200 |
| Indonesia Stock Exchange (IDX) | Indonesia | Mandatory | OJK Reg. 51/2017 · ISSB | All listed companies | Voluntary | ~956 |
| Stock Exchange of Thailand (SET) | Thailand | Phased | SEC Thailand 56-1 · ISSB | SET50 (2026), SET100 (2027) | Voluntary | ~50 |
| Philippine Stock Exchange (PSE) | Philippines | Mandatory | PFRS S1/S2 · SEC Philippines | All listed companies | Voluntary | ~288 |
| Pakistan Stock Exchange (PSX) | Pakistan | Phased | SECP ESG Guidelines · IFRS S1/S2 | All listed (phased) | Voluntary | Unknown |
| Tadawul | Saudi Arabia | Mandatory | CMA ESG Rules 2023 · ISSB | All listed companies | Voluntary | ~230 |
| DFM / ADX | United Arab Emirates | Mandatory | SCA Governance Regulations | All listed companies | Voluntary | ~120 |
| Qatar Stock Exchange (QSE) | Qatar | Mandatory | IFRS S1/S2 · QFMA · QSE ESG | All listed companies | Voluntary | ~50 |
| Boursa Kuwait | Kuwait | Mandatory | CMA Circular 04/2025 · ISSB | Premier Market premieres | Voluntary | ~39 |
| Muscat Stock Exchange (MSX) | Oman | Mandatory | MSX ESG Guidelines · IFRS S1/S2 | All listed companies | Voluntary | ~119 |
| Borsa Istanbul (BIST) | Turkey | Mandatory | TSRS (ISSB-aligned) · CMB | Assets > 1B TRY | Voluntary | ~100–150 |
| Egyptian Exchange (EGX) | Egypt | Phased | FRA Res. 107/108 · TCFD | Listed cos. ≥ EGP 100M | Voluntary | ~100–150 |
| Nairobi Securities Exchange (NSE Kenya) | Kenya | Mandatory | CMA ESG Guidance · NSE Manual | All listed companies | Voluntary | ~62 |
| Johannesburg Stock Exchange (JSE) | South Africa | Voluntary | King IV Code · JSE Sustainability Guidelines | Voluntary | Voluntary | Voluntary |
Scope, counts and obligation levels refer to issuers of listed shares. Issuers that only list bonds follow different rules depending on the venue. See section 3.5.
2. The Headline Numbers
Across the 37 stock exchanges mapped, ESG disclosure has effectively become the default operating standard for listed companies in 2026:
- 28 Mandatory regimes — full ESG / sustainability disclosure required for in-scope listed companies.
- 6 Phased regimes — disclosure being rolled out by company size, index membership, or fiscal year (Italy, Norway, Chile, Thailand, Pakistan, Egypt).
- 2 Voluntary regimes — TSX (Canada, after the CSA pause) and JSE (South Africa, comply-or-explain).
- 1 Suspended regime — the US federal SEC climate rule, partially compensated by California SB 253 / SB 261 for companies operating in the state.
- Scope 3 is mandatory in only 7 jurisdictions (mostly EU CSRD + ESRS-aligned), partial in India (BRSR Core), and voluntary almost everywhere else — including China, Hong Kong, Japan, Singapore, the Gulf, and Africa.
3. Analysis of Global Regulatory Trends
3.1. Convergence Towards ISSB Standards
The 2025-2026 period confirms the massive adoption of the International Sustainability Standards Board (ISSB) standards, specifically IFRS S1 (general requirements) and IFRS S2 (climate), as the global baseline. Major jurisdictions in Asia-Pacific (Australia, Singapore, Hong Kong, Malaysia, Indonesia, Thailand, the Philippines, Pakistan), Latin America (Brazil, Mexico, Chile, Colombia), the Gulf (Saudi Arabia, UAE, Qatar, Kuwait, Oman) and Africa (Kenya) have integrated these standards into their national legislation, often taking a "climate-first" approach (HKEX, SGX, ASX, LSE).
3.2. The US Pullback and European Revision
Contrary to the global trend, the United States has experienced a significant pullback. In March 2025, the SEC ended its defense of its climate disclosure rules following legal challenges and a change in administration. The federal regime is therefore counted as Suspended in our mapping. In practice, California's SB 253 and SB 261 still pull roughly 2,600 large companies operating in the state into mandatory climate and emissions disclosure, creating a de facto sub-national mandatory layer on top of NYSE and Nasdaq.
Concurrently, the European Union adopted the "Omnibus" package, which significantly reduced the scope of the CSRD by raising thresholds (from 250 to 1,000 employees) and exempting listed SMEs, while pushing back deadlines for certain companies. Even after Omnibus, however, the EU stack — CSRD, CSDDD, EU Taxonomy, EUDR, CBAM — remains the single most demanding sustainability regime in the world, and the only one where Scope 3 is broadly mandatory for in-scope companies on Euronext, Deutsche Börse, Nasdaq Nordic, Borsa Italiana, Madrid (BME) and Warsaw (GPW).
3.3. Chinese Regulatory Integration and the Manufacturing Context
The systematic integration of Chinese regulations is crucial for understanding the global supply chain. In April 2024, the Shanghai (SSE), Shenzhen (SZSE), and Beijing (BSE) stock exchanges issued guidelines making sustainability reporting mandatory for large-cap and dual-listed companies — an estimated 579 companies in scope for the 2025 fiscal year, reporting in 2026.
“The guidelines mandate that companies listed on the SSE 180 Index, STAR 50 Index, SZSE 100 Index, and ChiNext Index, as well as those dual-listed domestically and internationally, prepare and publicly disclose sustainability reports for the 2025 fiscal year by April 30, 2026.”
Supply Chain Risk Alert: For international buyers subject to complex regulations like the CSRD, the CSDDD (Corporate Sustainability Due Diligence Directive), or the Deforestation Regulation (EUDR), the Chinese manufacturing context presents traceability challenges. Although large Chinese companies are beginning to report their Scope 1 and 2 emissions, Scope 3 remains voluntary in China — and in fact in 30 of the 37 venues mapped here. Buyers must maintain heightened vigilance regarding the risks associated with a lack of transparency in deep value chains, as European penalties (which can reach up to 5% of global revenue under the CSDDD) will apply regardless of the local standards of suppliers.
3.4. Gulf, Africa and Emerging Markets Catch-Up
One of the clearest signals from the 2026 mapping is the speed at which the Gulf and Africa have closed the gap. Tadawul (Saudi Arabia), DFM/ADX (UAE), QSE (Qatar), Boursa Kuwait, MSX (Oman) and NSE Kenya all now operate under mandatory ESG disclosure regimes aligned with ISSB IFRS S1/S2. South-East Asia is also accelerating, with IDX (Indonesia), PSE (Philippines), SET (Thailand) and PSX (Pakistan) moving from guidance to mandatory or phased mandatory status. The era of "ESG only matters in Europe" is definitively over.
3.5. Listed Bonds vs Listed Shares: The Debt Blind Spot
This map counts listed companies. But a listing is not always equity. Thousands of issuers access capital markets only through bonds. Are they caught by the same ESG rules? Short answer: not always. It depends on what triggers the obligation.
Two logics coexist. In size-triggered regimes, the obligation follows the company’s size and any security admitted to a regulated market — shares or bonds — can be the gateway. This applies in the EU under CSRD, the UK Companies Act regime, Switzerland and Australia. In listing-rule regimes, the obligation sits in exchange rules for equity issuers, leaving bond-only issuers outside. This applies in Hong Kong, Singapore, mainland China, India and Japan.
Europe: bonds count, with three exits
Post-Omnibus, CSRD covers issuers with equity or debt admitted to an EU regulated market when they exceed 1,000 employees and €450 million in turnover. The Omnibus directive was published in the Official Journal on 26 February 2026. A bond-only issuer of that size reports like a listed company. Three exits remain:
- MTF listings: bonds on a multilateral trading facility, such as Luxembourg Euro MTF or Euronext Growth, are not admitted to an EU regulated market, so the listing itself triggers nothing.
- Wholesale debt: non-EU issuers with only debt listed in denominations of at least €100,000 can fall outside scope under the Transparency Directive exemption.
- Size: below the post-Omnibus thresholds, a bond listing no longer brings a company into scope.
The United Kingdom has two layers. The FCA’s TCFD-aligned listing rule targets equity issuers, but the Companies Act climate disclosure regulations also cover UK companies with more than 500 employees and transferable securities — including bonds — admitted to a UK regulated market. In Switzerland, Art. 964a CO covers public-interest companies, including those with outstanding bonds, from 500 FTEs and CHF 20 million in assets or CHF 40 million in revenue.
Asia: bond-only issuers are mostly outside
- HKEX: Appendix C2 applies to equity issuers. Chapter 37 professional-investor debt issuers are not required to publish an ESG report.
- SGX: Rule 711A sits in the continuing obligations for equity issuers; the debt-securities chapter has no equivalent.
- SSE / SZSE / BSE: the 2024 guidelines target companies with listed shares, including specified indices and dual-listed firms. Bond-only issuers, including many state-owned enterprises and LGFVs, remain outside; green-bond disclosure is instrument-specific.
- India: BRSR is mandatory for the top 1,000 listed entities by market capitalisation, but voluntary for high-value debt-listed entities.
- Japan: SSBJ standards apply through the securities reports of Prime Market companies, an equity-listing segment.
Australia is the exception: AASB S2 is triggered by company size under the Corporations Act rather than by security type, so large debt-listed entities can be caught. In the United States, the question is currently moot: the SEC climate rule would have covered debt-only registrants but is no longer defended, while California SB 253 and SB 261 depend on revenue and doing business in California, not on listing.
| Venue | What triggers the obligation | Bond-only issuers covered? |
|---|---|---|
| EU regulated markets | Size + any security on a regulated market | Yes above 1,000 employees and €450M; not for MTF listings or non-EU wholesale debt |
| London Stock Exchange | FCA listing rule (equity) + Companies Act (size) | Partly: Companies Act yes above 500 employees; FCA rule no |
| SIX Swiss Exchange | Art. 964a CO: public-interest company + size | Yes, from 500 FTEs |
| NYSE / Nasdaq | SEC rule suspended; California rules use revenue | Not relevant: listing is not the trigger |
| HKEX | Listing Rules for equity issuers | No for Chapter 37 debt |
| SSE / SZSE / BSE | Exchange guidelines and index membership | No |
| SGX | Rule 711A for equity issuers | No for Chapter 3 debt |
| NSE / BSE India | LODR; top 1,000 by market capitalisation | No; voluntary for high-value debt-listed entities |
| Tokyo Stock Exchange | FIEA / SSBJ; Prime Market | No |
| ASX | Corporations Act and company size | Yes, when size thresholds apply |
For the other venues in the map, rules are generally written for companies with listed shares. Until confirmed venue by venue, treat bond-only issuers as likely out of scope.
The green-bond layer is different. The EU Green Bond Standard, applicable since December 2024, the ICMA Green Bond Principles and China’s Green Bond Principles regulate the instrument rather than the issuer. They require disclosure on use of proceeds and impact, not entity-wide emissions or Scope 3.
Why this matters for supply chains: many large Asian manufacturers and state-owned groups finance themselves through dim sum bonds in Hong Kong, the Chinese exchange bond market or Euro MTF listings. For a buyer subject to CSRD or CSDDD, ‘listed’ does not mean ‘disclosing’. Check whether a supplier lists shares or only debt. Do not assume the data exists — ask for it.
4. Enforcement and Assurance Levels
The requirement for external assurance (audit) is becoming the norm to guarantee the reliability of ESG data:
- Reasonable Assurance: India (SEBI) is a pioneer in requiring "reasonable assurance" (the highest level, equivalent to a financial audit) on key indicators of the BRSR Core for the Top 150 companies, expanding progressively.
- Limited Assurance: Europe (CSRD) and Australia (ASRS) impose limited assurance initially, with a planned transition to reasonable assurance by 2028-2030.
- Penalties: Financial regulators (FCA in the UK, ASIC in Australia, AMF in France, CMA in Saudi Arabia, SCA in the UAE) are now integrating ESG misstatements (greenwashing) into their scope of penalties for securities fraud.
常见问题
参考资料
- BDO Insights — CSRD Post-Omnibus Revised Scope and Requirements
- Taylor Wessing — The UK's progress towards a Sustainability Disclosure Requirements framework
- Net Zero Compare — Switzerland Ordinance on Climate Disclosures (CH TCFD)
- SEC Press Release — SEC Votes to End Defense of Climate Disclosure Rules
- Dentons — Canadian Securities Administrators pauses climate-related and diversity-related disclosure rules
- Net Zero Compare — Brazil CVM Resolution 193: ISSB-aligned sustainability
- EY — Mexican Sustainability Reporting Standards
- CarbonSuite — China Mandatory Climate Regulations
- Freshfields — New climate disclosure requirements for Hong Kong-listed companies
- EY Japan — What's next for Japanese sustainability disclosure standards
- SGX Group — Extended timelines for most climate reporting requirements
- Glocert International — BRSR Core Assurance Readiness Guide for Indian Companies
- ESG Today — Korea Plans Mandatory Sustainability Reporting Beginning in 2028
- Lee Tsai & Partners — 2025 Mandate: Sustainability Reporting Mandatory for All Taiwan's Listed Companies
- CMS Law — Malaysia launches National Sustainable Reporting Framework
- Persefoni — ASRS Explained: Australia's Implementation of the ISSB Standards
- Charles Russell Speechlys — ESG considerations in the UAE
- Moroglu Arseven — Türkiye Raises Thresholds for Mandatory Sustainability Reporting
- Lexology — Changes on the Horizon for ESG Disclosures in South Africa
- Linklaters — EU Omnibus I: CSRD and CS3D amendments finalised
- Linklaters — CSRD impact on non-EU companies with EEA-listed equity or debt
- Harvard Law School Forum — CSRD and the wholesale debt exemption
- UK Companies (Strategic Report) (Climate-related Financial Disclosure) Regulations 2022
- SIX — Swiss Code of Obligations Art. 964a
- HKEX — Appendix C2 Environmental, Social and Governance Reporting Code
- SGX — Rule 711A
- SSE — Guideline No. 14 on Sustainability Reports
- SEBI BRSR FAQs for high-value debt-listed entities